Chari: Building the Financial Infrastructure Morocco’s Small Merchants Never Had.
FOUNDER SNAPSHOT
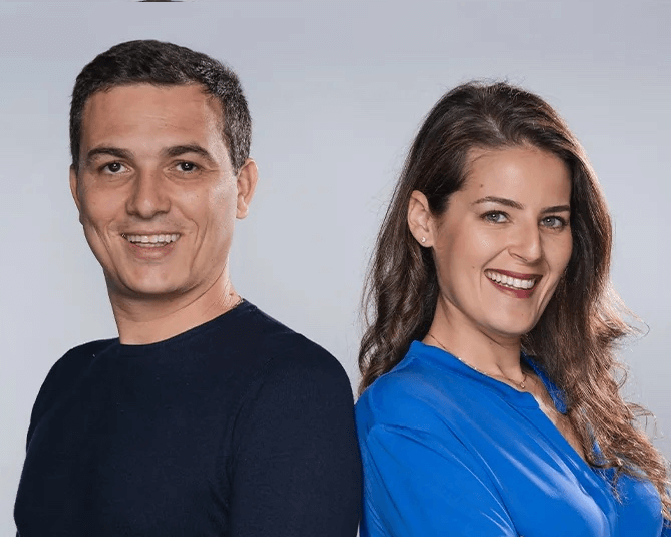
Ismael Belkhayat and Sophia Alj
STARTUP
Chari
STAGE
Growth, Series A closed
GEOGRAPHY
Morocco, Casablanca,
SECTOR
FinTech
Building for the Merchants Everyone Else Ignored
In Morocco, small, independent mom-and-pop shops account for about 80% of retail sales, with an estimated 200,000 scattered across the country.
Yet, for small shopkeepers, restocking can be very tasking and stressful. Many shut their doors to trek to cash-and-carry warehouses, losing sales and paying for transport.
Others tend to rely on small-scale wholesalers with old trucks and limited product ranges. That can mean that deliveries could be late and prices uncompetitive.
However, the founding insight behind Chari did not just come from a single market research report.
It came from boots-on-the-ground discoveries, real curiosity and numerous interactions with thousands of shopkeepers currently facing these problems.
Chari is set out to change the narrative for Morocco’s Small Merchants.
The Founder Before the Company
The co-founder, Ismael Belkhayat began his professional career in 2009 at the Paris office of the Boston Consulting Group before he returned to Morocco to launch the first web incubator in the country, Wib.co.
He later founded VotreChauffeur, a ride-hailing startup operating in Casablanca and a few other Moroccan cities.
The startup quickly became a household name in the country and, after about four years, was acquired for an undisclosed amount by Avis Car Rental.
While still running his first startup, he founded another one, Sarouty, a marketplace that facilitates real estate deals in Morocco.
Sarouty helps people to discover, buy or rent land and houses across Morocco. Sarouty quickly became the leading real estate platform in the country.
It partnered with PropertyFinder Group, a Dubai-based multinational proptech startup, to scale its tech and expand to more cities.
Due to the potential of the business, PropertyFinder opted for acquisition instead of partnership.
By the time Chari was founded in 2020, the founder was not learning how startups work. He was applying a decade of accumulated pattern recognition to a new and harder problem.
The Core Problem
The problem Chari is solving has two layers, and the second one only became visible once the first was underway.
After learning that 70% of the Moroccan population is either unbanked or unable to prove recurring income, Chari decided to put lending in the hands of the retailers by offering financial services such as micro credit or payment services.
Traditional retailers know their clients to the core; in a country of 40 million people and about 200,000 stores, each shopkeeper serves around 200 customers daily.
The e-commerce layer, free 24-hour delivery of FMCG inventory ordered through an app, solved the logistics problem.
But it revealed something structurally more significant underneath it. These businesses were generating real economic activity without a financial identity.
They could not access credit. They could not accept digital payments. They could not prove their income to a bank because the banks had never designed products for them.
The shopkeeper was not just underserved by the logistics system. She was invisible to the financial system entirely.
As Belkhayat explains:
E-commerce alone is almost impossible to make profitable.
The pivot was not an abandonment of the original vision. Rather, it was a recognition that the original product was the entry point, and the real opportunity was what came after trust was established.
The Strategic Decision Layer
Just as Chari pivoted from being primarily a distributor of consumer goods to focusing on fintech services, Belkhayat urges other founders to adapt their business models to market realities.
He has seen many startups fail because they could not make that shift.
The e-commerce model generated merchant relationships and trust at scale. Rather than trying to make that model profitable on its own terms, Chari used those relationships as the foundation for something with fundamentally better economics.
While, the inventory marketplace brought merchants onto the platform, the financial services layer is what retained them and generated sustainable margin.
Customers stayed because the transition was gradual, never abrupt. The merchant who trusted Chari for deliveries was not disrupted by the evolution to financial services.
They were offered additional tools by the same partner who had already proven reliable.
Over the past three years, Chari has built in-house the full technology stack required to operate under its financial institution license.
According to the founder:
Now that our rails are fully operational and supporting Chari’s needs, we are opening them to third parties.
Chari also plans to launch a Banking-as-a-Service model, allowing other startups and corporations to use its infrastructure to build their own financial tools, similar to Stripe or Revolut in Europe.
This transforms Chari from a company that serves merchants into a company that also serves other builders, creating an entirely new revenue category on infrastructure that was already built and paid for.
On reflection the founder revealed that even though the initial operations of Chari are did capture the bigger cities (like Rabat and Casablanca) however, the highest user stickiness is in the smaller cities where the underserved population is most concentrated and where the absence of alternatives makes Chari’s value proposition most acute.
Ecosystem Context
Chari has become the first VC-backed startup in Morocco to be granted a payment institution license by Bank Al-Maghrib, the country’s central bank.
A payment institution license from a central bank is not just an administrative formality. It is a fundamental legitimacy signal.
It means the regulator has audited Chari’s technology, compliance architecture, KYC and anti-money laundering processes, and risk management framework, and determined that the company meets the standards required to operate as a financial institution.
For a startup, that validation is categorically different from any investor backing.
The AI layer the founder describes is specifically applied to compliance and security, the areas where the regulatory requirements are most demanding.
Building AI tools for fraud detection, KYC processing, and money laundering risk assessment is not a product feature in the conventional sense.
Rather, it is the infrastructure required to operate legally at scale in a licensed financial services environment.
The regulatory moat that this creates is significant. In November 2022, Chari received a payment institution licence from Morocco’s central bank, allowing it to offer a range of financial services.
Any competitor attempting to replicate Chari’s current service offering would need to obtain the same license. That process takes years. Chari has already completed it.
The startup’s growth is underpinned by Morocco’s $250 billion retail market, where traditional retailers account for 80% of FMCG sales.
That market size, combined with the regulatory licence and the in-house technology stack, creates a structural position that is considerably more defensible than a product advantage alone would produce.
Observed Patterns
The repeat founder pattern observed thus far is substantively different from how it typically appears in startup narratives.
Three exits across three different business categories, ride-hailing, real estate, and now fintech, suggests a founder whose advantage is not sector expertise but market expertise.
The specific market is Morocco’s emerging digital economy. The skill being applied is how to build trust with Moroccan users and businesses, how to navigate the regulatory environment, and how to sequence products so that each one creates the foundation for the next.
One thing Belkhayat prides himself in is the ability to quickly focus on the next important thing rather than wallow in the glory or loss of the past.
That disposition, treating each company as a chapter rather than an identity, is visible in how Chari has been built.
The e-commerce chapter created merchant relationships. The fintech chapter monetised them. The BaaS chapter is now opening the infrastructure to the market.
Chari is enrolled in Y Combinator’s S21 program and is described as Morocco’s first startup accepted into the programme.
That distinction gives Chari access to a global founder network and investor community that most Moroccan startups cannot reach through domestic ecosystem channels alone.
Open Variables
The company’s merchant operating system has expanded well beyond digital ordering.
Although what is less visible is how far that ecosystem can extend.
The founder acknowledged that Chari has already entered digital banking and suggested that becoming a fully licensed bank remains a possibility over the longer term.
Whether that evolution ultimately positions the company alongside financial institutions or creates an entirely new merchant infrastructure category remains to be seen in the longer term.
Another open variable concerns market depth.
By remaining concentrated in Morocco rather than pursuing continental expansion, Chari is effectively betting that deeper penetration within one market creates greater long-term value than broader geographic reach.
That strategy appears internally coherent, although its long-term economics will become clearer as the company progresses toward later funding stages.
Why This Matters
Chari reflects an important shift within African fintech.
Many early fintech companies focused on bringing consumers into digital finance.
Chari instead concentrates on the businesses that sit underneath local economies.
Small merchants remain the final distribution point for millions of households across Africa.
Helping those businesses access banking, payments, credit and operational software has implications that extend beyond commerce itself.
The company also challenges another common startup assumption.
Expansion is not always the primary measure of ambition.
Sometimes the stronger strategic position comes from dominating one market before attempting another.
Final Strategic Takeaway
The population most underserved by the formal financial system, the people Chari was built for, are not in the places that attract the most startup attention.
They are in the smaller cities, the places where a digital wallet and a payment terminal represent access to infrastructure that has never existed before.
Nevertheless, the corner shop that could not keep its door open while restocking is now a node in Chari’s licensed financial network.
The founder who noticed that problem five years ago is now building the rails that other companies will use to serve the next version of the same customer.
In emerging market fintech, the distance between those two sentences is what durable competitive advantage looks like.
This article is drawn from an in-depth founder interview conducted by Afriq IQ with Ismael Belkhayat, Co-founder of Chari. Selected insights and observations are published here.
Ready to Ace Your Next Funding Pitch?
Join thousands of founders who have improved their pitch skills and secured funding with our automated interview simulator.