MyItura: Tackling the Healthcare Problem That Begins When Patients Cannot Afford to Be Treated
FOUNDER SNAPSHOT
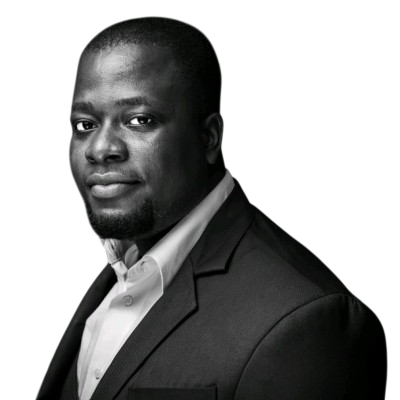
Shina Arogundade
STARTUP
MyItura
STAGE
Pre-revenue
GEOGRAPHY
Nigeria
SECTOR
HealthTech
Background
MyItura began with a broad ambition to build technology for healthcare. Its direction has since expanded beyond digitising medical processes towards a problem that is more immediate for many patients: how to pay for treatment when the need arises.
The company combines digital health services with MediLoan, a healthcare-focused credit product designed to help eligible patients access treatment without having to fund the entire cost upfront.
It is also developing more direct ways to reach communities through field agents and a pilot health kiosk.
The underlying idea is that healthcare access is not determined by the availability of doctors and facilities alone. It is also shaped by whether patients can afford to use them.
The Core Problem
Healthcare can be available but financially inaccessible
A patient may reach a hospital, receive a diagnosis and know what treatment is needed, yet still leave without receiving care because they cannot afford the bill.
The founder understands this problem personally and described an experience in which a dental procedure costing substantially more than his insurance coverage left him needing to raise an additional finance.
He said it took him three months to gather the money while living with the pain.
For MyItura, this illustrates a gap between having some form of health insurance and having sufficient financial protection when treatment is required.
It is whether a patient can complete the journey from needing treatment to actually receiving it.
Healthcare services are fragmented
The company subsequently developed tools for telemedicine and laboratory test booking and fulfilment.
These services addressed different parts of the patient journey, but the broader ambition was to connect them.
That matters because patients do not experience healthcare as a collection of separate software categories.
They experience a sequence of needs that includes finding care, consulting a professional, getting tested, paying for treatment and keeping track of their medical information.
A platform that connects these steps has the potential to address a more meaningful problem than one that digitises any single step in isolation.
The Strategic Decision Layer
MyItura’s evolution reflects a shift from building tools for healthcare providers towards addressing the patient’s ability to access care.
The company’s MediLoan product is central to that shift. Rather than disbursing money directly to patients, approved financing is paid to healthcare providers.
The provider receives payment upfront, while the patient repays over an agreed period.
The model is designed to address two connected problems:
- Patients may not have the money required to pay for treatment immediately.
- Healthcare providers need confidence that they will be paid for the services they deliver.
Paying providers directly creates a connection between financing and the healthcare service being purchased.
It also means the model depends on effective coordination among MyItura, patients and participating providers.
MediLoan can be used for a range of healthcare needs, including services delivered through hospitals, laboratories and pharmacies.
MyItura has also integrated AI into several parts of its platform.
These include speech-to-text transcription and summarisation, automatic generation of clinical notes, and preliminary interpretation of laboratory tests before a patient speaks with a doctor.
These capabilities may reduce administrative work and help connect information across the patient journey.
But AI is not the most distinctive part of MyItura’s broader proposition.
Its potential value lies in how technology, healthcare services and financing work together.
Automating a consultation note is useful. Helping a patient complete a consultation, obtain the necessary tests and afford the resulting treatment addresses a wider system problem.
The Ecosystem Context
MediLoan operates at the intersection of healthcare and financial services.
Its viability depends not only on demand for treatment, but also on the ability to assess applicants, make appropriate credit decisions and recover repayments.
MyItura had benefited from improvements in identity verification, know-your-customer (KYC) checks and credit-bureau infrastructure.
Guarantors are used in cases where applicants lacked conventional credit histories, including people connected to cooperatives.
These mechanisms point to a difficult balancing act.
The product is intended to help people who cannot readily pay for treatment upfront. Yet extending credit to people with limited financial capacity creates risks of its own.
A healthcare financing product must make treatment more accessible without pushing patients into repayment obligations they cannot sustain.
The wider healthcare ecosystem also matters.
Hospitals must be willing to participate, laboratory and pharmacy services must be coordinated, and patients must understand the product well enough to use it.
MyItura’s partnerships with providers could become important distribution channels, but the company still faces the work of building those relationships one institution at a time.
This has been identified as a broader problem in African healthtech.
Unlike sectors where established payment rails or distribution networks can be reused, healthcare often lacks a ready-made channel through which new services can reach large numbers of people.
Observed Signals
The product has evolved in response to market constraints
MyItura’s original health-records focus proved difficult to commercialise with the capabilities and purchasing power available at the time.
The company expanded into telemedicine, test booking and other services, while AI later made some previously difficult features more feasible.
This history suggests an iterative approach to product development.
Financing is connected to the service itself
MediLoan is designed to pay healthcare providers directly rather than give cash to patients.
That links the financing product to a specific treatment or service and may make the proposition more tangible to participating providers.
The model’s long-term strength, however, will depend on repayment performance, the cost of acquiring and serving customers, and the ability to maintain sufficient lending liquidity.
The company is combining digital and physical delivery
The use of field agents and a pilot health kiosk suggests that MyItura is not assuming an app alone will solve the access problem.
This could help the company reach people who are poorly served by conventional digital channels.
It also creates a more operationally demanding model.
Evidence of sustained use, affordable delivery and repeatable economics will be important in determining whether the approach can scale.
Open Variables
Can MediLoan scale responsibly?
The core test is whether the company can consistently assess repayment capacity, recover loans and maintain access to capital without undermining the affordability it is trying to create.
Can the model reach people who need it most?
Patients with limited income or limited access to formal banking may face the greatest barriers to healthcare.
They may also be the hardest customers to assess and serve through conventional credit models.
Can MyItura build repeatable distribution?
Provider partnerships and community-based access points could help, but scaling them requires operational capacity, funding and sustained cooperation from healthcare institutions.
Will the integrated platform create a stronger business?
Telemedicine, laboratory bookings, medical records and healthcare financing can reinforce one another.
But each introduces different operational requirements and revenue dynamics.
The company needs to show that integration creates enough value to justify the complexity.
Why This Matters
For investors, MyItura sits at an interesting intersection of healthtech, fintech and service-delivery infrastructure.
It is addressing a problem that cannot be solved by digitisation alone and that is, the financial gap between needing healthcare and being able to pay for it.
For healthcare providers, a model that delivers approved payments upfront could help reduce the number of patients unable to proceed because of immediate affordability constraints.
For patients, spreading payments could make some forms of treatment more accessible provided the credit is appropriate and repayment terms are manageable.
For governments, health insurers and development finance institutions, the wider question is whether financing mechanisms can complement efforts to expand coverage and improve access to essential care.
MyItura’s approach may offer useful lessons, but its broader impact would depend on evidence of responsible lending, sustained patient use, provider participation and measurable healthcare outcomes.
Final Strategic Takeaway
MyItura began by building tools for healthcare.
It is now attempting to connect several parts of the healthcare journey, with financing at the centre of its effort to make treatment more accessible.
Its most important proposition is not simply that patients can consult a doctor online, book a test or store medical records.
It is that these services become more useful when patients can also overcome the financial barrier that prevents them from receiving care.
That is a more demanding problem than building a healthtech application.
It requires technology, provider relationships, responsible credit decisions, physical distribution and sufficient liquidity to operate together.
This article is drawn from an in-depth founder interview conducted by Afriq IQ with Shina Arogundade, CEO and Founder of MyItura. Selected insights and observations are published here.
Ready to Ace Your Next Funding Pitch?
Join thousands of founders who have improved their pitch skills and secured funding with our automated interview simulator.